If you have spent money on your business before becoming VAT registered, you may be able to get some of the VAT back, but only if you follow HMRC’s rules on timing, evidence and use.
At The Taxcom, we are a Manchester-based tax advisory and accountancy firm, and we regularly help new businesses work out what they can recover. Before you register, it helps to understand the wider VAT registration requirements, because your registration date drives every claim in this guide.
This article explains what pre VAT registration expenses are, which ones qualify, how far back you can go and how to include them on your first VAT return.
What Are Pre-VAT Registration Expenses?
Pre VAT registration expenses are costs a business pays before it becomes VAT registered, where suppliers charged VAT on the goods and services. They are also called pre registration expenses, pre registration costs or pre registration purchases.
Normally, only a business registered for VAT can recover VAT. GOV.UK allows you to reclaim VAT paid on goods or services bought before registration, within set time limits, as long as the purchases are for the business now registered. This is the main VAT reclaim route open to a newly registered business.
Typical examples include:
-
Goods purchased as stock or raw materials before registration and still held when you register.
-
Equipment, computers or machinery bought before registration and still used in the business.
-
Services obtained shortly before registration, such as legal, accounting, marketing or consultancy fees.
Once the claim is allowed, the VAT on pre registration purchases is treated as input VAT. Input VAT is the VAT a business has paid on its own purchases. It is the figure you set against the VAT you charge customers. Our guide to input VAT vs output VAT explains how the two interact on a return.
The legal basis is regulation 111 of the Value Added Tax Regulations 1995. It gives HM Revenue and Customs (HMRC) discretion to let a taxable person treat VAT incurred before registration as input tax. HMRC applies that discretion through its published guidance, so you should follow it closely.
|
Type of purchase |
How far back you can go |
Key condition |
|---|---|---|
|
Goods (stock, equipment, certain capital assets) |
4 years before your registration date |
Still held, or used to make goods you still hold |
|
Services (fees, marketing, software) |
6 months before your registration date |
Services relate to your taxable business activity |
HMRC Rules for Reclaiming VAT on Pre-Registration Expenses
The ability to reclaim VAT on pre registration expenses is not automatic. The overarching principle is that the purchase must relate to your business purpose, meaning the taxable supplies you make after registration. These rules apply to both goods and services. You must also follow the standard UK VAT registration process so that your registration date is set correctly.
1. Goods: The Four-Year Rule
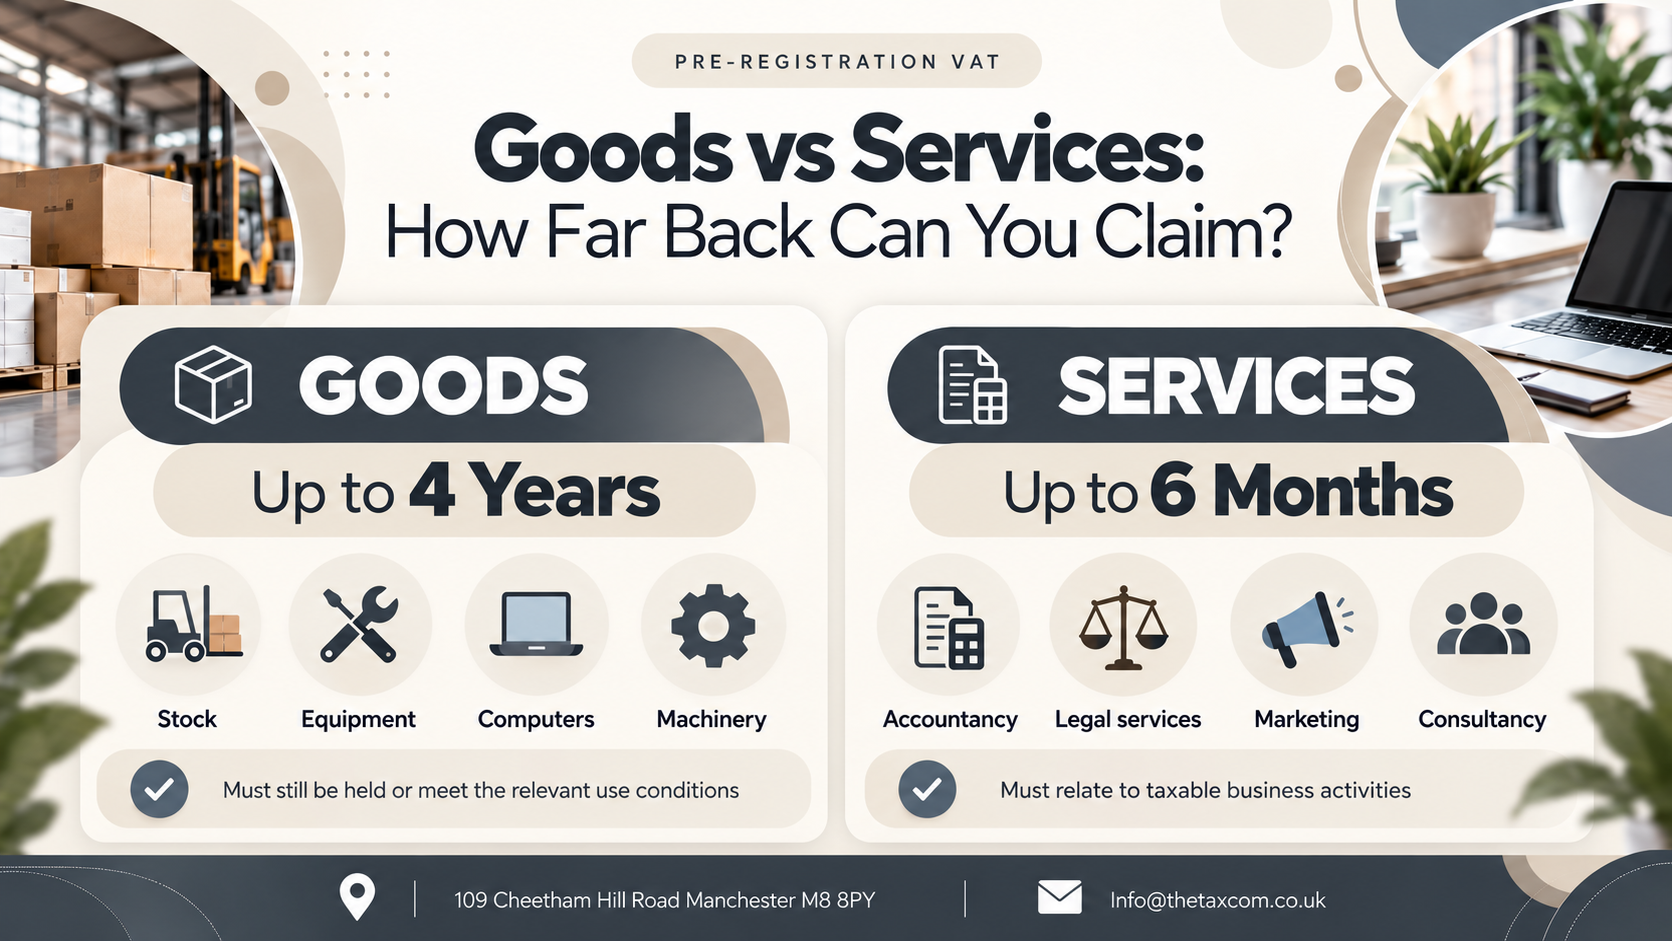
You can reclaim VAT on goods bought up to four years before your registration date. This four year time limit applies provided that:
-
The goods were bought by the same legal entity that is now VAT registered.
-
You still have the goods, or they were used to make other goods you still hold.
-
They were bought for business purposes and not for private use.
2. Services: The Six-Month Rule
VAT on services purchased can be reclaimed for a shorter window: up to six months before your registration date. The services must relate to your taxable business, and the business activity carried on after registration must make taxable supplies. Examples include accountants’ and solicitors’ fees, marketing campaigns, consultancy, web design and staff training.
3. Exclusions and Restrictions
Even inside the time limits, some VAT cannot be recovered. The main exclusions are:
-
Goods used up: items consumed before registration, such as fuel, electricity and gas.
-
Goods sold: stock or assets sold or supplied before your registration date.
-
Linked services: services relating to goods you disposed of before registering.
-
Exempt supplies: exempt goods or services made with the purchase, or use for non-business activities.
-
Private use: only the business proportion can be claimed where an item is also used personally.
-
Cars: the usual motor car restrictions still apply, so a car bought before registration will rarely qualify in full.
4. Evidence Requirements
You must hold a valid VAT invoice for each purchase. The invoice should show the supplier’s name, address and VAT number, the date and the VAT charged. A card receipt or bank statement alone is not enough. It is sensible to check the VAT number of a supplier if an invoice looks unusual. Without a valid VAT invoice, the claim will normally be refused.
5. Business Continuity
HMRC looks at whether the goods or services genuinely feed into your taxable activities after registration. A laptop bought 18 months before registration and still in use can qualify. If it was sold or replaced before your registration date, the claim fails.
6. Capital Goods Scheme Items
Pre registration VAT on items within the capital goods scheme is outside the usual route. Regulation 111 itself refers to capital items of a description falling within regulation 113 as an exception. The scheme covers land and buildings costing £250,000 or more before VAT, and individual computers or similar items costing £50,000 or more. If you have bought property or high-value equipment, take advice before you claim.
Types of Pre VAT Registration Expenses That Qualify
Not every cost qualifies. To claim pre registration VAT successfully, you need to know which categories of goods and services usually work and which are restricted.
1. Stock and Inventory
Stock is the most common category. If you bought taxable goods before registering and still hold them on your registration date, you can usually reclaim the VAT. Examples include:
-
Raw materials used for production.
-
Goods purchased for resale.
-
Packaging that is unused and still on hand.
If part of the stock has already been sold, you can only claim the VAT on the part you still hold. Exempt goods are treated differently, because VAT linked to exempt supplies is not recoverable. You must also be able to show the goods were bought for the business.
2. Capital Assets and Equipment
Many start-ups invest in machinery, IT hardware or furniture before they register. Where these certain capital assets are still used in the business when you register, the VAT may be reclaimed. Examples include computers, printers, specialist tools, vans used for trade, and fixtures and fittings. Where you used an asset in the business before registering, HMRC may expect you to apportion the claim, so keep a note of how you reached your figure.
3. Professional and Advisory Services
Start-ups often engage chartered accountants, lawyers or consultants before registration. VAT on these services can be recovered if they were supplied within six months of your registration date and relate to the business. Examples include accountancy fees for setting up financial systems, legal advice on forming a limited company or drafting contracts, and consultancy on marketing or business planning.
4. Property-Related Expenses
VAT on fit-out costs, surveys, architectural fees and planning applications may be recoverable if the usual conditions are met. Property is where claims most often become complicated, particularly where the option to tax or the capital goods scheme is involved.
5. Marketing, IT and Training
Marketing often starts before formal registration. If the services were supplied within the six-month window, the VAT may be recoverable. This includes website development, branding and advertising campaigns, and training courses that benefit your taxable activities. Software licences or subscriptions that you still use may also count, depending on whether they are goods or services in the particular case.
Time Limits for Reclaiming Pre-VAT Registration Expenses
HMRC applies strict time limits to pre registration VAT. If an expense falls outside them, you lose the VAT even if the cost was clearly for the business. Both limits are counted back from your registration date, not from the date you applied or the date you received your VAT number.
The Four-Year Rule for Goods
VAT on goods can be reclaimed if you bought them within four years before your registration date and still hold them. Goods bought more than four years earlier cannot be claimed, even if they remain in stock.
The Six-Month Rule for Services
VAT on services can be reclaimed only if the services were supplied within six months before your registration date. For example:
-
Legal fees for setting up a limited company qualify if they fall within the six months.
-
IT consultancy used to build a system installed just before registration may qualify.
-
A web design invoice from nine months before registration would not qualify.
The Deadline for Making the Claim
Pre registration VAT should be claimed on the first VAT return you are required to make. If you miss it, treat it as an error to be corrected. In any event, the claim cannot be made more than four years after the date the first return was due. Regulation 111 sets out both the time limits and the claim procedure. If your first return is already filed without the claim, speak to an adviser promptly rather than waiting. Keeping to the right VAT deadlines also helps you avoid penalties on that first return.
Grey Areas and HMRC Interpretation
Some situations need care:
-
Software licences: a licence bought 18 months before registration and still in use may be treated as goods, but the classification depends on the facts.
-
Fit-out costs: works carried out within four years may qualify if the property remains in business use.
-
Mixed-use expenses: where a purchase has both business and personal use, only the business proportion can be claimed.
-
Utilities and fuel: these are usually treated as consumed before registration, so the VAT is not recoverable.
How to Reclaim VAT on Pre-Registration Expenses
To reclaim VAT on pre registration purchases, you include the amount on your return. No separate form or special box is needed. Errors are common where records are incomplete or the registration date is misjudged, so work through the steps below in order. Other businesses may have different rules if they are in a VAT group or use a special scheme.
-
Confirm your registration date: check the effective date on your VAT registration certificate. If you crossed the VAT threshold, the date may be earlier than the day you applied. The registration threshold is currently £90,000 of taxable turnover over a rolling 12 months, and our guide to the current VAT threshold explains when you must register.
-
Identify eligible purchases: list goods purchased within four years that you still hold, and services obtained within six months, that relate to your taxable supplies.
-
Gather documents: collect a valid VAT invoice for each item. Add contracts, lease agreements or service agreements where they help show what was bought.
-
Apportion mixed use: split VAT where an item has business and personal use. GOV.UK gives the example that if half of your mobile phone calls are personal, you can reclaim 50% of the VAT.
-
Include the claim on your first VAT return: add the eligible VAT to the input VAT figure in Box 4, alongside VAT on purchases made after registration. This is how you claim input VAT for the pre registration period.
-
Keep a schedule: record each item, the date, the supplier, the VAT amount and why it qualifies, in case HMRC asks to see it.
Worked Example: Claiming Pre Registration Input VAT
Your registration date is 1 March 2026. You hold stock bought 10 months earlier for £12,000 plus £2,400 VAT, and all of it is still unsold. You also bought a laptop 14 months ago for £1,200 plus £240 VAT, which you still use fully for the business. In the last four months you paid an accountant £600 plus £120 VAT, and 9 months ago you paid a web designer £1,800 plus £360 VAT.
|
Item |
VAT paid |
Claimable? |
Reason |
|---|---|---|---|
|
Stock (goods, 10 months) |
£2,400 |
£2,400 |
Within four years and still held |
|
Laptop (goods, 14 months) |
£240 |
£240 |
Within four years and still in use |
|
Accountant (services, 4 months) |
£120 |
£120 |
Within six months |
|
Web design (services, 9 months) |
£360 |
£0 |
Outside the six-month limit |
|
Total |
£3,120 |
£2,760 |
You would add £2,760 to Box 4 on your first VAT return, together with VAT on purchases made after registration. The web design VAT of £360 is lost because the service is outside the six-month window.
Partially Exempt Businesses
If you make both taxable and exempt supplies, you are a partially exempt business. You cannot recover input VAT linked to exempt supplies, whether it was incurred before or after registration. Only the taxable proportion is recoverable. If you use the Flat Rate Scheme, you do not charge VAT in the usual way on your sales and the scheme limits what you can reclaim, so check how it affects your first return before you file.
When Specialist Help Makes Sense
Large claims, property costs and mixed supplies attract attention. HMRC may check pre registration claims, particularly where the amounts are significant. If a claim is questioned, you may need specialist support during VAT investigations.
Common Mistakes With Pre-Registration VAT Claims
-
Claiming VAT on goods that were sold or used up before the registration date.
-
Counting the time limits from the date you applied rather than your effective registration date.
-
Claiming without a valid VAT invoice, or using a receipt that does not show the VAT.
-
Claiming 100% of VAT on items that are partly for personal use.
-
Treating services older than six months as if the four-year goods rule applied.
-
Forgetting the claim on the first VAT return and not correcting it later.
-
Reclaiming VAT on costs linked to exempt supplies without checking partial exemption.
Getting Your Pre-Registration VAT Claim Right With The Taxcom
Our team can help you work out what you can recover and put it on your return correctly.
-
VAT Services: At The Taxcom, we help with VAT registration, returns and compliance, including reviewing your pre-registration purchases and preparing the schedule that supports your first claim.
-
Tax Advisory: We can advise on the best time to register and how to structure early spending, so you reduce the VAT you lose to the time limits.
-
VAT Investigations: If HMRC questions a pre-registration claim, we can help you respond and deal with the dispute.
Frequently Asked Questions
What are pre VAT registration expenses?
They are business costs on which you paid VAT before your business became VAT registered. You may be able to reclaim that VAT on goods bought within four years and services bought within six months, if the conditions are met.
How far back can I claim pre registration VAT?
You can go back four years for goods you still hold and six months for services. Both periods are counted back from your registration date.
Can I reclaim VAT on pre registration purchases without a VAT invoice?
No, you need a valid VAT invoice for each purchase. HMRC may accept other evidence only in limited cases where you have made genuine efforts to obtain the invoice.
Where do I claim pre registration VAT on my VAT return?
Add it to the input VAT in Box 4 of your first VAT return. There is no separate box or form for pre registration amounts.
Can I reclaim VAT on a limited company’s costs from before it was incorporated?
Possibly. Regulation 111 can allow it where the person who paid was connected to the company and was reimbursed, and the purchase passes the goods and services tests. Take advice before claiming.
Can I reclaim VAT on goods I have already sold?
No. VAT on goods sold or used up before your registration date cannot be reclaimed. If only part of the stock is sold, you can claim on the part you still hold.
Get Your Pre-Registration VAT Claim Right
If you are about to register or have just registered, the next step is to check your purchases against the four-year and six-month limits. Our VAT Services team covers registration, returns and compliance, so your first return includes every claim you are entitled to.
If you need broader planning around registration timing and cash flow, our Tax Advisory team can help. We offer a free initial consultation and are open Monday to Saturday 8am to 6pm and Sunday 11am to 4pm from our Manchester office. Contact The Taxcom to book a personal consultation.
This is general guidance, not professional advice. Contact our tax advisors for personalised advice.